Understanding Polish company law is essential for entrepreneurs and foreign investors planning to establish a business in Poland. The country’s legal framework offers several corporate structures, each with different requirements for ownership, liability, capital, management, and taxation. Three important options are the Spółka z ograniczoną odpowiedzialnością (Sp. z o.o.), Spółka Akcyjna (S.A.), and Spółka Komandytowa (Sp.k.). Choosing the appropriate structure can influence operational flexibility, financial exposure, and long-term business growth.
Understanding Polish Company Law
Polish companies operate primarily under the Commercial Companies Code, which regulates company formation, corporate governance, shareholder rights, and management responsibilities.
The legal structure determines how a business operates, how decisions are made, and who bears responsibility for its obligations.
For international entrepreneurs, Poland offers access to the European Union and opportunities across Central European markets. Businesses considering expansion can review UCI’s international company formation solutions before deciding on their corporate structure.
What Is a Sp. z o.o. in Poland?
A Spółka z ograniczoną odpowiedzialnością (Sp. z o.o.) is a private limited liability company and one of Poland’s most commonly used business structures.
It is particularly suitable for SMEs, foreign subsidiaries, consulting businesses, trading companies, and international entrepreneurs.
Share Capital Requirements
The minimum share capital for a Sp. z o.o. is PLN 5,000, with a minimum nominal share value of PLN 50.
Shareholders contribute capital in exchange for ownership interests. Their liability is generally limited, although directors may face personal liability in specific circumstances.
Management and Ownership
A Sp. z o.o. can generally be established by one or more shareholders, subject to certain statutory restrictions.
Its main management body is the management board, which represents the company and manages its operations.
A supervisory board is not mandatory for every Sp. z o.o., making the structure relatively straightforward for smaller businesses.
What Is an S.A. in Poland?
A Spółka Akcyjna (S.A.) is a joint-stock company generally suited to larger businesses requiring substantial investment, formal governance, or access to capital markets.
Unlike a Sp. z o.o., an S.A. operates through a more structured corporate framework.
Share Capital Requirements
An S.A. requires minimum share capital of PLN 100,000.
Its capital is divided into shares, making the structure appropriate for businesses planning to attract multiple investors or undertake larger financing arrangements.
Corporate Governance
An S.A. generally requires three principal corporate bodies:
- Management board
- Supervisory board
- General meeting of shareholders
The management board handles company operations, while the supervisory board oversees management activities.
This structure provides formal oversight but creates additional administrative responsibilities.
When Is an S.A. Suitable?
An S.A. may be appropriate for businesses planning significant investment, complex ownership arrangements, or potential stock exchange participation.
However, establishing an S.A. solely for prestige may create unnecessary costs and compliance obligations.
What Is a Sp.k. in Poland?
A Spółka Komandytowa (Sp.k.) is a limited partnership that combines two categories of partners with different liability arrangements.
Unlike a Sp. z o.o. or S.A., a Sp.k. is a partnership rather than a capital company.
General Partners
General partners – komplementariusze – are responsible for managing and representing the partnership.
They generally bear unlimited liability for partnership obligations, subject to the applicable legal rules.
Limited Partners
Limited partners – komandytariusze – have liability limited according to the statutory partnership arrangements, including the registered liability amount known as suma komandytowa.
Their financial exposure should not be assumed to equal only their capital contribution.
Capital Requirements
A Sp.k. has no statutory minimum share capital requirement.
However, partners must establish their contributions and responsibilities through the partnership agreement.
This structure may suit businesses where some participants manage operations while others primarily provide investment.
Sp. z o.o. vs S.A. vs Sp.k. – Key Differences
The following comparison highlights the principal differences between these Polish business structures.
| Requirement | Sp. z o.o. | S.A. | Sp.k. |
|---|---|---|---|
| Legal structure | Limited liability company | Joint-stock company | Limited partnership |
| Minimum capital | PLN 5,000 | PLN 100,000 | No statutory minimum |
| Ownership | Shareholders | Shareholders | General and limited partners |
| Liability | Generally limited | Generally limited | Depends on partner category |
| Management | Management board | Formal board structure | General partners |
Each structure serves different commercial objectives. Entrepreneurs should assess both immediate requirements and future plans before incorporation.
Which Polish Company Structure Offers Better Liability Protection?
Liability protection is an important consideration when comparing Polish company structures.
A Sp. z o.o. generally protects shareholders from direct responsibility for company debts. However, management board members may face liability in certain situations, including circumstances involving unsuccessful enforcement against the company.
An S.A. also provides limited shareholder liability, although its directors and supervisory bodies have specific statutory responsibilities.
A Sp.k. operates differently because general partners generally bear unlimited liability, while limited partners benefit from more restricted exposure under the applicable rules.
For entrepreneurs prioritising shareholder liability protection, a Sp. z o.o. may offer a more practical structure than a traditional limited partnership.
Also read – LLC vs Ltd vs SAS vs GmbH
How to Register a Company in Poland
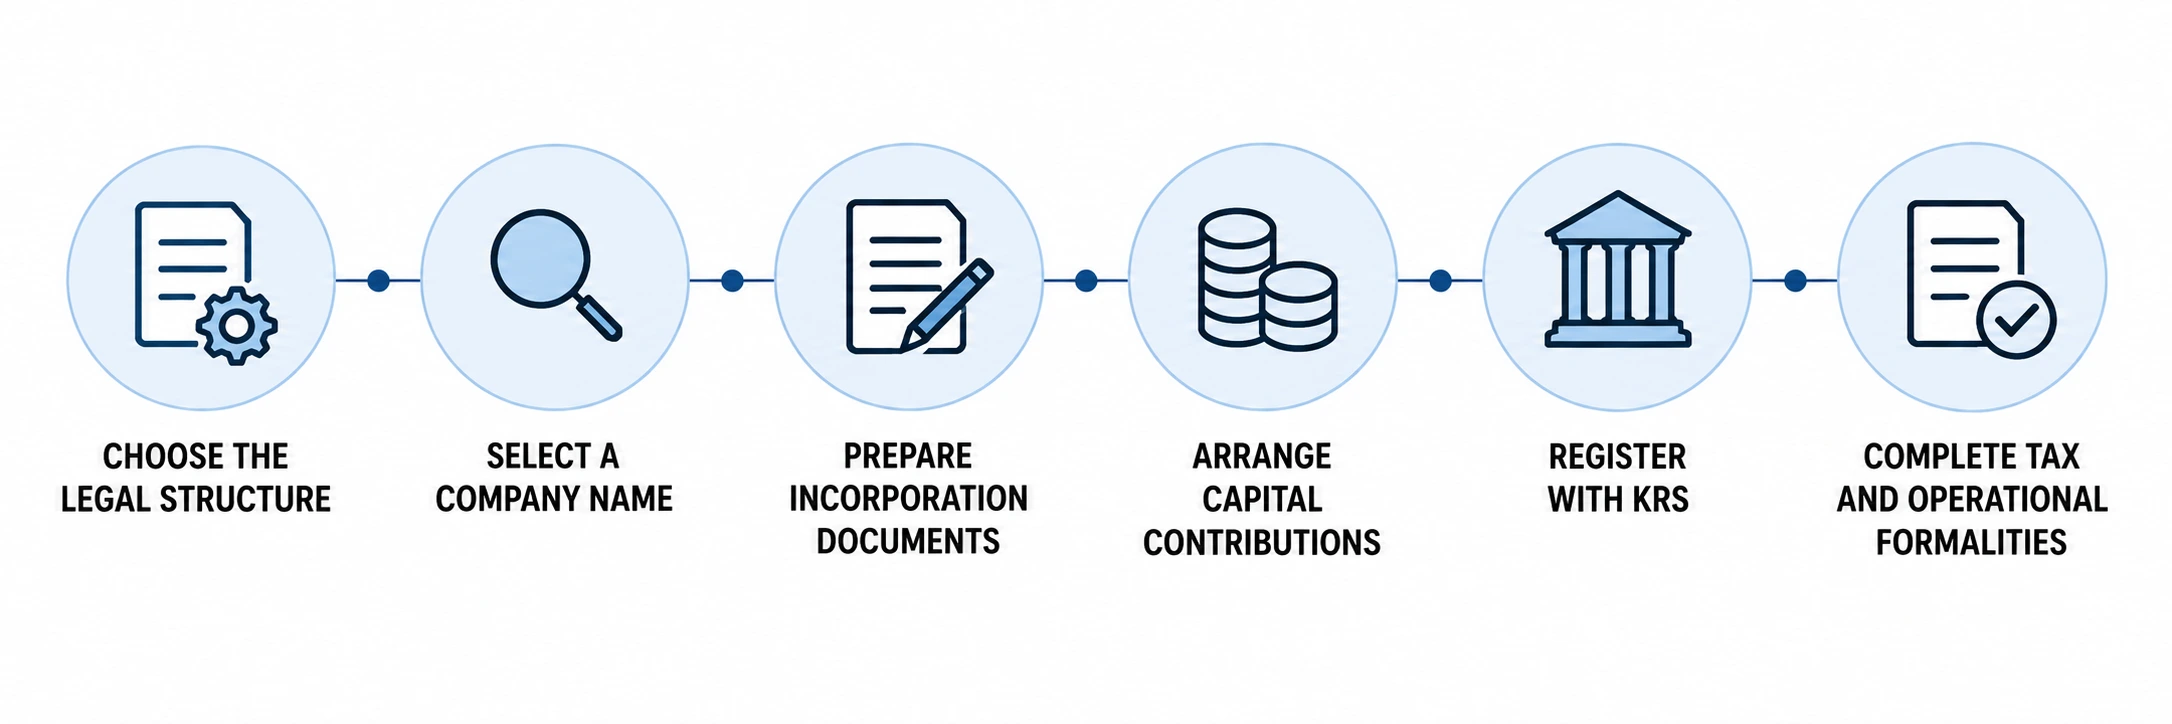
The incorporation process depends on the selected legal structure, but several requirements are common.
1. Choose the Legal Structure
Determine whether a Sp. z o.o., S.A., or Sp.k. aligns with your ownership, liability, investment, and management requirements.
2. Select a Company Name
Choose a suitable company name that meets Polish registration requirements and includes the appropriate legal designation.
3. Prepare Incorporation Documents
Prepare the articles of association or partnership agreement, including ownership, management, capital, and business activity information.
4. Arrange Capital Contributions
Provide the required capital or partnership contributions according to the selected structure and applicable legal requirements.
5. Register with KRS
Submit the incorporation application to the National Court Register (Krajowy Rejestr Sądowy – KRS).
Eligible structures may use electronic registration procedures, while others require notarial documentation.
6. Complete Tax and Operational Formalities
Confirm the company’s NIP and REGON identification details, assess VAT registration requirements, arrange banking, and complete any additional business registrations.
Foreign investors may also need to provide translated or authenticated corporate documents.
Taxation of Polish Companies
Tax treatment differs between company structures and should be assessed before incorporation.
Corporate Income Tax
Poland’s standard Corporate Income Tax (CIT) rate is generally 19%.
A reduced 9% CIT rate may apply to qualifying taxpayers and eligible income, subject to statutory conditions.
Sp. z o.o. and S.A. companies are generally subject to corporate income tax.
Importantly, a Sp.k. is also generally a CIT taxpayer under Polish law, despite being legally classified as a partnership.
VAT and Other Tax Obligations
Businesses may need to register for VAT depending on their activities and applicable exemptions.
The standard Polish VAT rate is 23%, with reduced rates available for certain transactions.
Companies should also consider dividend taxation, partner-level taxation, payroll obligations, and cross-border tax arrangements.
Tax treatment can significantly affect the overall cost of operating through each structure.
Ongoing Legal and Compliance Requirements
After registration, Polish businesses must comply with applicable accounting, reporting, and corporate obligations.
Common requirements include:
- Maintaining accurate accounting records
- Preparing annual financial statements
- Filing applicable corporate tax returns
- Updating company information in KRS
- Meeting beneficial ownership reporting requirements
- Complying with employment and payroll regulations
The exact requirements depend on the legal structure, business activity, and ownership arrangements.
Businesses operating internationally should also assess transfer pricing, VAT, and cross-border reporting obligations where applicable.
UCI’s legal and compliance support can help international businesses manage relevant corporate obligations.
Which Polish Company Structure Should You Choose?
The right structure depends on your commercial priorities.
Choose a Sp. z o.o. when you need a relatively straightforward limited liability company for trading, consulting, subsidiaries, or SME operations.
Consider an S.A. when your business requires substantial capital, formal corporate governance, or potential access to public investment markets.
Consider a Sp.k. when your business model benefits from distinct general and limited partner roles and you understand the associated liability and tax implications.
Foreign entrepreneurs should also consider shareholder residency, financing requirements, administrative costs, and long-term expansion plans.
Conclusion
Polish company law provides several options for entrepreneurs and international investors. A Sp. z o.o. offers limited liability and operational flexibility, an S.A. provides a more formal framework for larger businesses, and a Sp.k. combines different partner responsibilities within a partnership structure.
Before making a decision, businesses should assess capital requirements, management obligations, taxation, liability exposure, and long-term objectives. For assistance with selecting and establishing the right Polish company structure, contact UCI to discuss your requirements.